
ENERGY · INDUSTRIAL POLICY
America’s energy-storage boom depends heavily on affordable Chinese cells. A sweeping new restriction could reveal how difficult—and expensive—it is to break that connection.
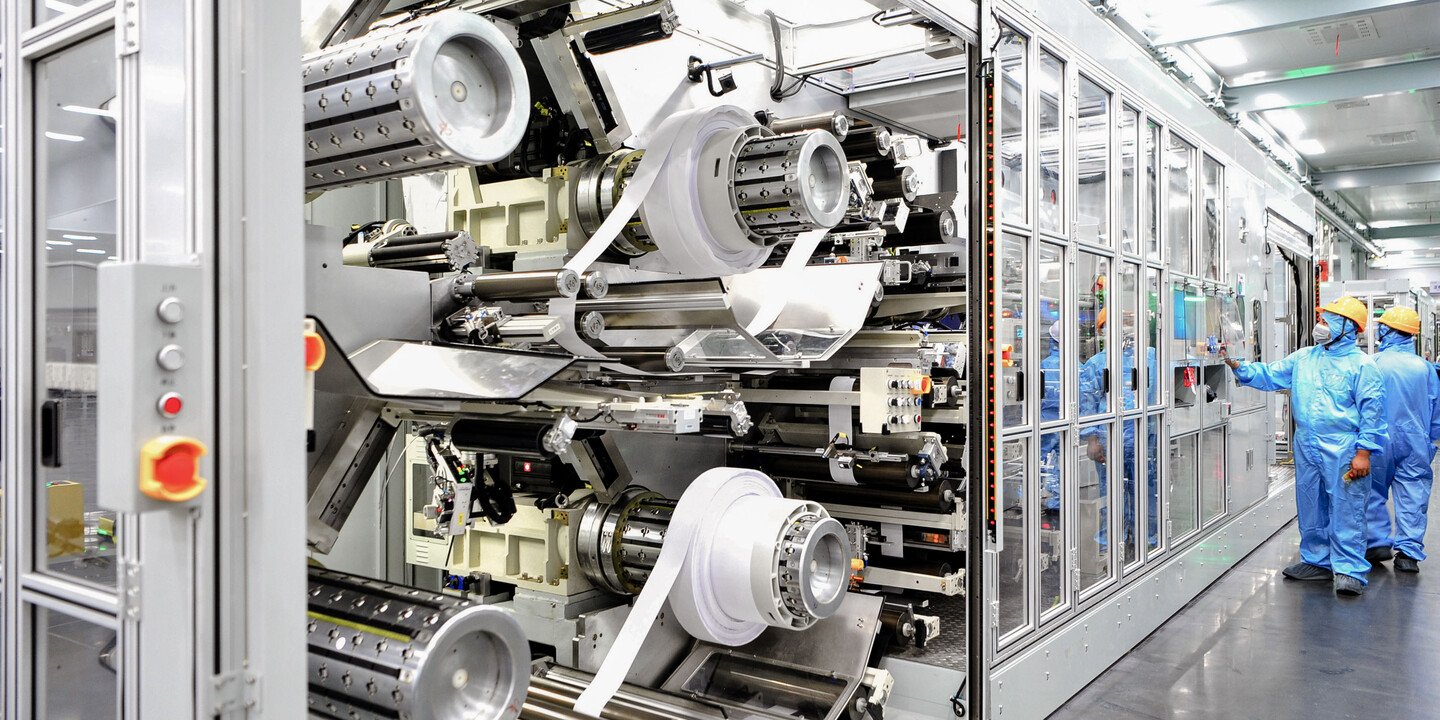
Battery storage is expanding across the United States at record speed. The new capacity can steady an increasingly complex grid, improve reliability during periods of high demand, and hold electricity from wind and solar until customers need it.
That progress carries a geopolitical contradiction. Much of it has been enabled by low-cost cells made in China, even as Washington has spent years trying to reduce Chinese influence over critical energy supply chains. A late-August executive order from the Trump administration now pushes that effort much further by effectively excluding Chinese batteries from large grid-storage systems.
The order turns a familiar trade-off into an urgent policy test. Cheap, mature technology can accelerate clean-energy construction today. Building a more independent supply base may reduce strategic exposure tomorrow, but doing so can also raise prices and slow projects while domestic factories catch up.
From Incentives to a Ban
Until now, US policy had generally tried to redirect the market through eligibility rules and added costs. The Inflation Reduction Act tax credits created in 2022 placed conditions on where battery minerals could be extracted, processed or recycled and where cells and components could be assembled.
Those incentives changed in 2025, but the underlying goal survived. Beginning in 2026, new legislation requires 55% of the material cost in an eligible energy-storage project to originate outside China and other restricted countries. Projects that miss that threshold cannot receive the federal tax credit.
Tariffs apply another layer of pressure. The US import tax on batteries rose from 7.5% to 25% in January. Together, the credit rules and tariffs narrow China’s price advantage without completely removing its products from the market.
The executive order takes a sharper approach. It declares a national emergency and prohibits foreign-made equipment for the bulk-power system when it creates a national-security risk. Battery storage systems are named, alongside inverters and transformers.
Shan Tomouk, who leads energy-storage work at the industry-analysis firm Benchmark Mineral Intelligence, says the move surprised the sector. A blanket prohibition, rather than another financial disincentive, creates uncertainty even for US companies trying to plan domestic projects.
The Near-Term Disruption
For developers, the first effect may be delay rather than instant replacement. BloombergNEF expects grid-connected storage growth to slow in the near term as companies wait to learn precisely which equipment, suppliers and projects fall within the restriction.
The Department of Energy is expected to issue detailed guidance by the end of the year. Depending on that interpretation, some projects could have to switch to US-made cells or imports from countries other than China. Isshu Kikuma, an energy-storage analyst at BloombergNEF, warns that either route will probably cost more; in the hardest cases, the added expense or uncertainty could cause projects to be abandoned.
The order’s language can also be read to cover equipment that is already operating. Strict enforcement would be enormously disruptive because Chinese cells are used in most battery plants currently connected to the US grid. Kikuma therefore considers it unlikely that existing facilities will be forced offline solely because of where their batteries were produced.
A Domestic Supply Is Coming
America may eventually be able to supply the cells it needs. On paper, planned factories could provide enough manufacturing capacity around 2030. In practice, plants often open slowly, operate below their stated capability, or never reach it, so actual domestic output may not match demand until later in the 2030s.
Several large projects could improve the balance sooner. Facilities involving Ford, SK On, LG Energy Solution and Samsung SDI are scheduled to begin production or increase output by next year. The cooling market for electric vehicles is unexpectedly helping grid storage: some factories originally intended to make EV batteries are being converted to produce stationary-storage cells.
Capacity, however, is not price parity. Batteries made in the United States remain substantially more expensive than Chinese products. Turning to another major producer such as South Korea would diversify supply, but those imports would probably cost more too. Strategic independence therefore carries a bill for developers, customers, taxpayers, or some combination of all three.
The Larger Technology Dilemma
Beyond batteries, the dispute captures a challenge facing countries pursuing cleaner energy. China has built commanding positions in both battery and solar-panel manufacturing through sustained public support, accumulated research, and years of industrial experience. Its scale now makes many technologies cheaper and easier to deploy.
Using those products can cut energy costs and emissions faster. Depending too heavily on a single country for essential infrastructure can expose buyers to trade conflict, political leverage, logistical shocks or sudden rule changes. Neither concern is imaginary, and emphasizing one inevitably weakens the response to the other.
The central question is not simply whether the United States can remove China from its battery market. It is how quickly separation can happen without undermining the storage boom the country needs. The order puts security and domestic manufacturing first. Coming projects, prices and factory ramps will reveal how much energy progress that choice demands in return.